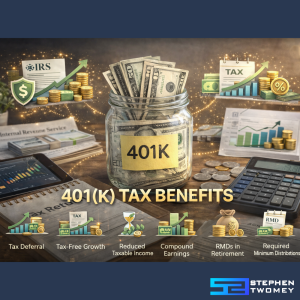
Yes, contributing to a traditional 401(k) generally reduces your current federal taxable income because contributions are made on a pre-tax basis. A Roth 401(k) works differently because contributions are made with after-tax dollars and do not reduce current taxable income.
For accredited investors, understanding this distinction is important when balancing retirement savings, current tax exposure, future income needs, and a broader wealth strategy.
Does Contributing to a 401(k) Reduce Taxable Income?
Traditional 401(k) contributions generally reduce the wages subject to federal income tax in the year the contribution is made. Instead of receiving all compensation as current taxable wages, an employee elects to defer part of that compensation into a retirement account.
For example, assume an employee earns $100,000 and contributes $15,000 to a traditional 401(k). Before considering other deductions and adjustments, the employee’s federal taxable wages would generally be reduced by that $15,000 contribution.
The basic calculation looks like this:
- Gross salary: $100,000
- Traditional 401(k) contribution: $15,000
- Remaining wages before other adjustments: $85,000
This does not mean the employee saves $15,000 in taxes. The contribution reduces the amount of income currently subject to federal income tax.
A traditional 401(k) does not eliminate taxes. It changes when the income is taxed.
How Much Can a 401(k) Contribution Reduce Your Taxes?
The actual tax savings from a traditional 401(k) contribution depend largely on the marginal tax rates that apply to the income being deferred.
Suppose an investor contributes $10,000 and the entire amount would otherwise fall within a 24% federal marginal tax bracket. The approximate current federal tax savings would be:
$10,000 × 24% = $2,400
At a 32% marginal rate, the same $10,000 contribution could produce approximately $3,200 in current federal income tax savings.
These are simplified examples. Filing status, other income, deductions, credits, state taxes, and the progressive structure of federal tax brackets can change the actual result.
The important distinction is between the reduction in taxable income and the reduction in taxes owed. A $10,000 traditional contribution may reduce current taxable wages by $10,000, but the tax savings represent only a percentage of that amount.
Traditional 401(k) vs. Roth 401(k): Which Reduces Taxable Income?
Traditional and Roth 401(k) accounts provide tax advantages at different stages.
Traditional 401(k)
Traditional 401(k) contributions are generally made before federal income tax is applied. This lowers current taxable wages while allowing investments inside the account to grow tax deferred.
Taxes generally become due when money is distributed from the account. Qualified retirement withdrawals from a traditional 401(k) are typically treated as ordinary taxable income.
This approach may appeal to investors who have relatively high marginal tax rates today and expect to face lower effective tax rates during retirement.
Roth 401(k)
Roth 401(k) contributions are made with after-tax dollars. They therefore do not reduce current taxable income.
The potential benefit comes later. Qualified Roth distributions can generally be withdrawn free from federal income tax.
An investor choosing between traditional and Roth contributions is therefore making a decision partly about when to pay taxes.
For investors accumulating significant assets, holding both traditional and Roth retirement assets can also provide tax diversification. Having multiple tax treatments available in retirement can create greater flexibility when determining where future income should come from.
Does a 401(k) Reduce Adjusted Gross Income?
Traditional 401(k) contributions generally reduce wages included in federal taxable income, which can also reduce adjusted gross income, or AGI.
That can matter because AGI is used throughout the federal tax system. Certain deductions, credits, and other tax provisions are subject to income thresholds or phaseouts.
Roth 401(k) contributions do not provide the same current reduction because Roth contributions are included in taxable wages.
Investors should remember that AGI is affected by more than retirement contributions. Business income, investment income, capital gains, deductions, and other financial activity can all influence the final calculation.
Do 401(k) Contributions Reduce Social Security and Medicare Taxes?
Traditional 401(k) contributions generally reduce wages subject to federal income tax, but they normally do not reduce wages subject to Social Security and Medicare taxes.
Consider someone earning $100,000 and contributing $15,000 to a traditional 401(k). The contribution may reduce federal taxable wages for income tax purposes, but Social Security and Medicare taxes are generally still calculated without excluding that elective deferral.
This distinction explains why increasing a traditional 401(k) contribution does not reduce every tax appearing on a paycheck.
401(k) Contribution Limits for 2026
The IRS periodically adjusts retirement contribution limits for inflation. For 2026, the standard employee elective deferral limit for 401(k) plans is $24,500.
Traditional and Roth employee contributions generally share this limit. An employee cannot ordinarily contribute $24,500 to a traditional 401(k) and another $24,500 to a Roth 401(k) under the same annual elective deferral framework.
Catch-Up Contributions
Employees age 50 or older may generally make additional catch-up contributions if their plan allows them.
For 2026, the general catch-up contribution limit is $8,000. That can bring total employee contributions to $32,500 for many eligible participants.
SECURE 2.0 also provides a higher catch-up limit for eligible participants ages 60 through 63. For 2026, that catch-up amount is $11,250, potentially allowing total employee deferrals of $35,750.
Certain higher earners making catch-up contributions may also be required to make those contributions on a Roth basis under SECURE 2.0 rules. Because Roth contributions are made after tax, those contributions would not provide the same immediate reduction in taxable income.
How Employer 401(k) Matching Affects the Decision
Employer matching can significantly increase the economic value of participating in a 401(k).
Suppose an employer contributes 50 cents for every dollar an employee contributes, up to 6% of compensation. An employee earning $100,000 who contributes at least $6,000 could receive another $3,000 from the employer under that formula.
For this reason, investors should avoid evaluating the tax reduction from a 401(k) in isolation. The employer match, investment options, plan fees, vesting requirements, and long-term tax treatment can all affect the value of participating.
Giving up a substantial employer match simply to invest elsewhere may materially change the economics of the decision.
When Does Using a Traditional 401(k) for Tax Reduction Make Sense?
Traditional 401(k) contributions can become particularly useful during high-income years.
Executives may receive substantial bonuses. Business owners can experience unusually profitable years. Professionals may see income rise sharply during the peak stages of their careers.
Increasing pre-tax retirement contributions can defer part of that income while building long-term retirement assets.
The strategy becomes more nuanced for investors with significant portfolios. A 401(k) may sit alongside Roth accounts, taxable brokerage accounts, real estate, private investments, and alternative investments.
Each serves a different purpose. Retirement accounts provide valuable tax treatment but have contribution and distribution rules. Taxable assets can provide greater liquidity. Private investments may offer access to different return drivers but can introduce additional risk, complexity, and illiquidity.
For high-net-worth investors, the question is therefore not simply how to minimize this year’s taxable income. The larger objective is to determine how different accounts and assets work together across decades.
Frequently Asked Questions
Does contributing $10,000 to a 401(k) reduce taxable income by $10,000?
An eligible $10,000 traditional 401(k) contribution generally reduces current federal taxable wages by $10,000. It does not reduce the actual tax bill by $10,000.
Does a Roth 401(k) reduce taxable income?
No. Roth 401(k) contributions are made with after-tax dollars and generally do not reduce current taxable income.
Can a 401(k) put you in a lower tax bracket?
Potentially. Traditional contributions reduce current taxable wages, which can reduce the amount of income falling into higher marginal tax brackets. Federal tax brackets are progressive, so moving below a threshold does not cause all income to be taxed at the lower rate.
Are 401(k) contributions tax deductible?
Traditional employee contributions generally are not claimed as a separate deduction on an individual tax return. The tax benefit is typically reflected through payroll because eligible pre-tax contributions are excluded from current federal taxable wages.
The Bottom Line
So, does contributing to a 401(k) reduce taxable income? Traditional 401(k) contributions generally do. Roth 401(k) contributions do not provide the same immediate tax reduction.
The more important question is whether receiving the tax benefit today supports the investor’s long-term strategy. Current tax rates, expected retirement income, employer matching, liquidity needs, and the balance between traditional, Roth, taxable, and alternative assets should all be considered.
For investors building substantial portfolios, a 401(k) is best viewed as one component of a broader retirement, tax, and capital allocation strategy.
Disclosure: This article is provided for general educational and informational purposes only. Nothing in this article or elsewhere on StephenTwomey.com constitutes financial, investment, tax, accounting, or legal advice. Tax laws and individual circumstances vary. Consult qualified financial, tax, and legal professionals before making investment or tax-planning decisions.
For perspectives at the intersection of entrepreneurship, capital allocation, and long-term business value creation, visit StephenTwomey.com.